- Ueno Bank’s collapse froze the savings of 60 percent of Paraguay’s adults and toppled a president in four days.
- Lebanon’s seven-year wait shows what Paraguay needs to get right in the next 90 days.
DUBAI: On Nov. 3, nearly 3 million people in Paraguay opened their banking app and found their money out of reach.
Ueno, a digital lender whose customers made up about 60 percent of the country’s adults, according to the Associated Press, had been seized overnight.
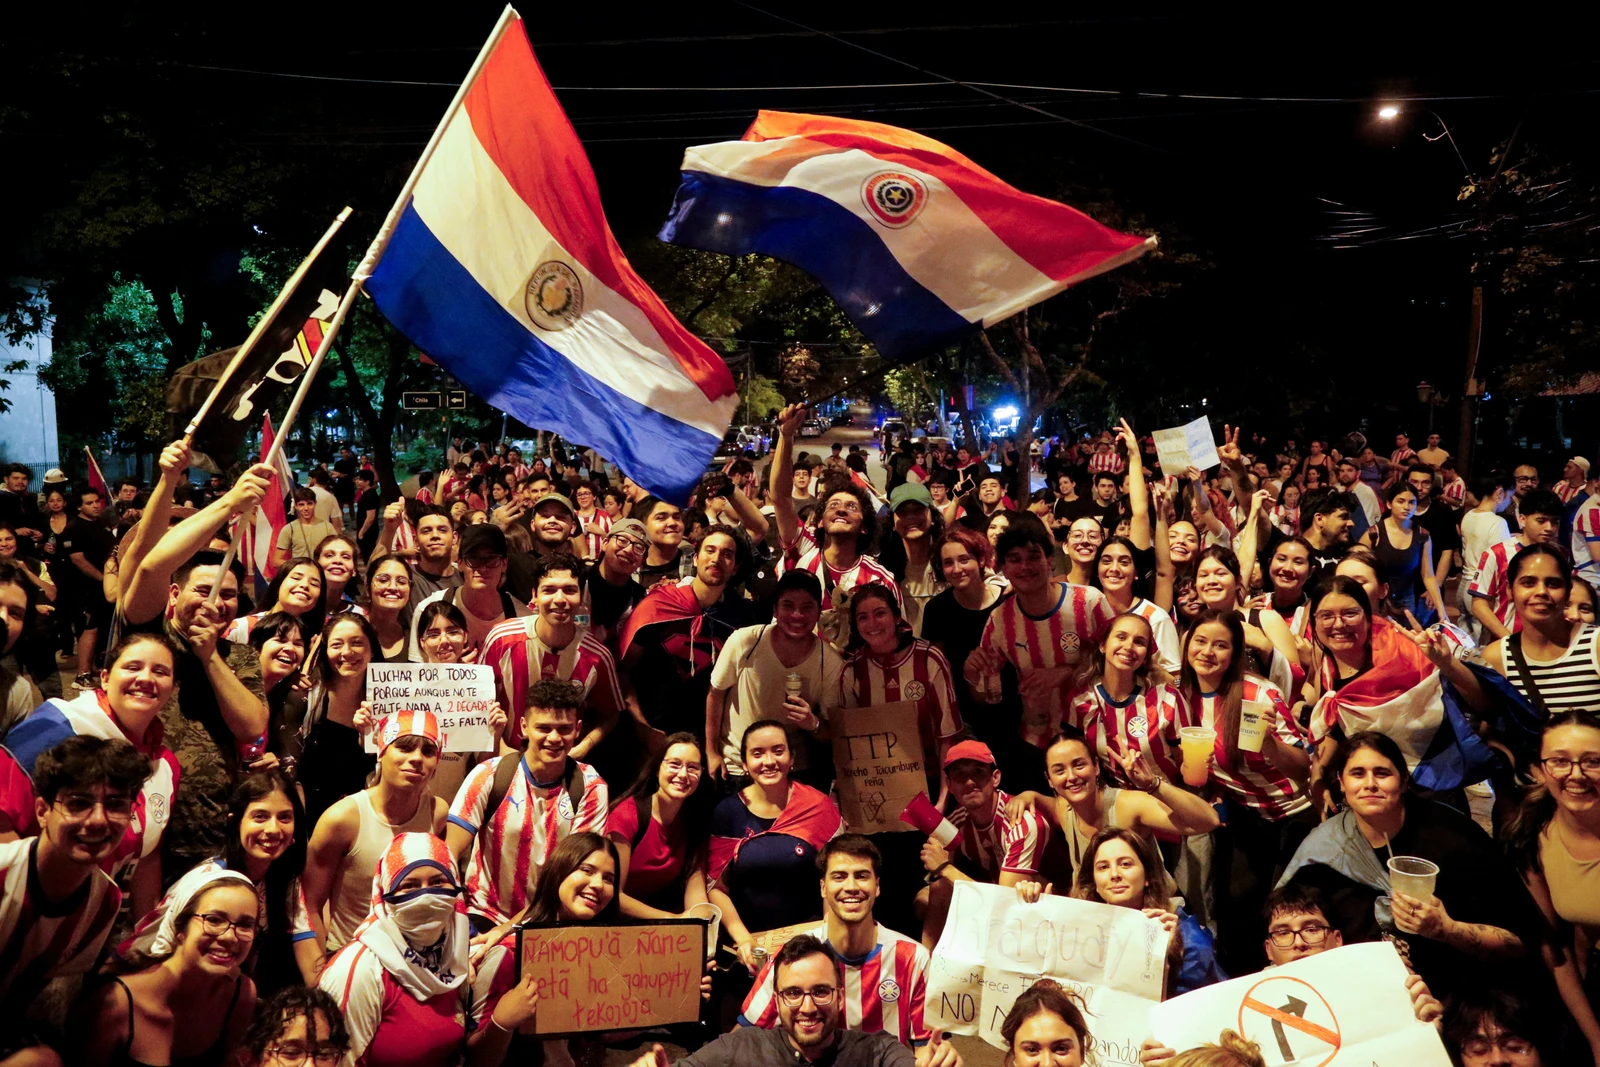
By Friday, the crisis had cost a president his job and his freedom, and AFP reported crowds gathered outside Congress chanting: “Give back the money.”
Seven years earlier, Lebanese savers lived the same nightmare. There are similarities between the two countries, according to economic experts.
“The strongest parallel is corruption and the bank–regulator–state link,” Nasser Saidi, president and founder of Nasser Saidi & Associates and former chief economist of the Dubai International Financial Centre, told Arab News.
“The main message is the importance of keeping politics away from central banking, monetary policy and regulatory oversight of the banking and financial system,” he added.
The scale, however, is very different. In Lebanon, Saidi said, the central bank’s scheme “tied together three interlinked balance sheets: a bankrupt government, banks with 75 percent of assets in government and central bank debt, and a central bank borrowing from banks to defend an overvalued currency and enable the Ponzi scheme.”
Paraguay has “none of that,” Saidi said. “Ueno’s failure came from insider and related party transactions at one bank, not from a central bank borrowing new money to pay old obligations.”
But the tests are the same: trust and accountability.
The trust that breaks first
“Lebanese depositors lost something more fundamental than money: the belief that what belongs to them is actually theirs,” said Rand Ghayad, a professor of economics at Harvard University, speaking to Arab News in a personal capacity.
“Imagine working your entire life, saving responsibly, only to discover that accessing your own money depends on the discretion of bankers and politicians. That kind of betrayal changes economic behavior for generations,” he added.
Ghayad argued that an event such as that seen on Nov. 3 leads people to “stop trusting banks.” It can also see businesses lose access to credit and an entire economy deprived of its ability to finance its future.
“You can replace lost money. But rebuilding lost trust can take generations,” said the economics professor.
Lebanon’s banks shut after protests erupted in October 2019 and reopened with curbs on dollar withdrawals.
“The closures led to panic and a bank run, then frozen payments and informal capital controls, then a massive credit crunch,” Saidi said. The Lebanese pound has since lost more than 98 percent of its value, and the state defaulted on its eurobonds, its dollar-denominated foreign debt, in March 2020.
The doom loop, inverted
“In Lebanon, the central bank (Banque du Liban) ran the biggest Ponzi scheme in history, greater than Madoff’s, through ‘financial engineering,’ high interest rates and borrowing from banks to protect a highly over-valued Lira,” Saidi said. “BDL’s losses likely exceed $70 billion.”
Paraguay ran the loop in reverse: the state financed the bank.
Ueno administered some $850 million in public funds, including about $380 million from the state pension and health fund, Reuters reported.
The central bank governor, Carlos Carvallo, had run Ueno’s predecessor before President Santiago Pena appointed him, AP reported.
The central bank said he recused himself from decisions on the lender.
The red flags were there. The central bank said it warned Ueno in June that it was lending too much to companies tied to its owners, and on a single day in September 2025 nearly $39 million went to three such companies, AP reported, citing the newspaper ABC Color.
Pena, a business partner of Ueno’s owner until March 2025, dismissed the concerns as a smear campaign.
The bank says he was never its shareholder, and Pena denies wrongdoing.
On Nov. 2, regulators put Ueno into resolution, a process that lets them move a failing bank’s deposits to healthier banks before selling off what remains, after its solvency ratio, a measure of its capital against its risks, fell below half the legal minimum, AP reported.
Counted by heads, not by dollars
Paraguay’s deposit guarantee covers up to 228.3 million guaranies ($36,564.64) per person, which the central bank says protects 97 percent of Ueno’s customers, AP reported.
The cap is fixed in local currency, meaning as as the guarani slid, its value fell from about $38,000 to closer to $35,000, by AP’s count.
“Confidence is not restored by statements alone. It is restored when people see that deposits are accessible, payments continue, losses are identified honestly, and the authorities are applying the rules fairly," said Walid Abousleiman, a financial expert.
“Depositors need proof, not reassurance,” he added.
The 97 percent also counts people, not money. “Moody’s estimated insured deposits were only around 30 percent of Ueno’s total deposit value,” Saidi said.
“A pension fund holds the savings of workers who trusted someone else to protect their retirement,” Ghayad said. “That's the fundamental injustice: people who never made the gamble end up paying for it.”
Saidi had a clear message to Paraguay for how to move forward. “Do the opposite of what Lebanon did,” he said.
“Paraguay’s lesson is to put a number on Ueno’s hole quickly, through an independent audit of its assets, and say who bears it, starting with its shareholders.”
The firewall Lebanon never had
Paraguay’s public debt is about a third of gross domestic product, according to Fitch Ratings.
In Lebanon, Saidi said, “debt-to-GDP stood at an unsustainable 155.2 percent in 2025.”
That fiscal room is Paraguay’s firewall, and investors are testing it.
Despite investment-grade ratings from Moody’s and S&P Global, Paraguay’s bonds posted some of the worst losses in emerging markets this week, AP reported.
“No informal limits should spread to healthy banks, since that is what turned Lebanon’s bank closures into a system-wide freeze and failure,” Saidi said.
“Any liquidity support given to other banks should be collateralised and conditional,” Abousleiman said. “The purpose is to protect the payment system and prevent contagion—not to use public money to quietly absorb private losses.”
Accountability at a different speed
Pena submitted his resignation as president on Nov. 5, with the Senate removing him from office the next day.
Prosecutors placed him under house arrest on suspicion of breach of trust, summoned him to answer allegations including influence peddling, and ordered central bank governor Carvallo’s arrest, AP reported.
The swift actions in South America contrast with the slower pace seen in Lebanon. The Middle Eastern country’s central bank governor of 30 years, Riad Salameh, was arrested in September 2024, nearly five years after the collapse, over alleged financial crimes he denies, Reuters reported.
Seven years on, the International Monetary Fund says a new staff-level agreement, the preliminary deal that precedes any IMF loan, still requires an appropriate financial gap law, which would decide who absorbs Lebanon’s losses, Reuters reported.
“Lebanon’s greatest failure wasn't the banking collapse itself. It was spending seven years refusing to decide who would pay for the losses,” Ghayad said.
The 90-day test
Paraguay’s new president, Pedro Alliana, has promised the nearly 3 million affected depositors that they will not be abandoned, AFP reported.
“If they delay, give mixed messages, or appear to protect certain interests at the expense of others, a single bank failure could turn into a wider credibility crisis,” Abousleiman warned.
“Banking crises are won or lost in the first 90 days, not the next seven years,” Ghayad said. “The longer you postpone the reckoning, the more a financial crisis becomes a crisis of public trust.”
Saidi warned that the lesson for Paraguay is that losses do not shrink while officials wait.
“They move onto depositors, pensioners and the wider economy,” he said, adding: “Justice delayed is justice denied.”